Beyond Actuarial Tables: How Real-Time Data Is Reshaping Risk and Pricing
⚠️ Truyện hư cấu phục vụ giải trí. Nhân vật & tình tiết là sản phẩm tưởng tượng.
For centuries, the insurance industry has rested on a foundational pillar: the actuarial table. These historical grids of numbers, probabilities, and population averages dictated what you paid for your life, health, or car insurance based on broad demographic buckets. Age, gender, zip code, and profession served as blunt proxies for risk. If you fell into a certain statistical cohort, you were assigned a corresponding price, regardless of whether your individual lifestyle flatly contradicted the group average. But that era is drawing to a rapid close. We are living through a profound transformation in how risk is understood, measured, and priced, driven by the convergence of artificial intelligence, real-time wearables, and vast oceans of big data.
To understand this shift, we must first look at the traditional model of insurance, which was fundamentally reactive and collective. Risk pooling has always been the bedrock of insurance, spreading the financial burden of unexpected tragedies across a large population. Yet, traditional risk pooling relied heavily on lagging indicators. Insurers looked backward at past data to predict future claims, creating a world of generalized averages where safe drivers subsidized reckless ones, and exceptionally healthy individuals paid the same health insurance rates as those with chronic lifestyle risks. It was an imperfect science born out of necessity because the data required to evaluate individuals in real time simply did not exist.
Today, that data gap has vanished. The rise of insurtech startups and the digital transformation of legacy carriers have ushered in an era of predictive analytics and algorithmic underwriting. Instead of asking what the average person in your age group did last decade, modern underwriting asks what you are doing right now. This is the shift from static, historical pricing to dynamic, hyper-personalized policy pricing. It changes the fundamental social contract of insurance, turning it from a static safety net into an active, continuous behavioral feedback loop.
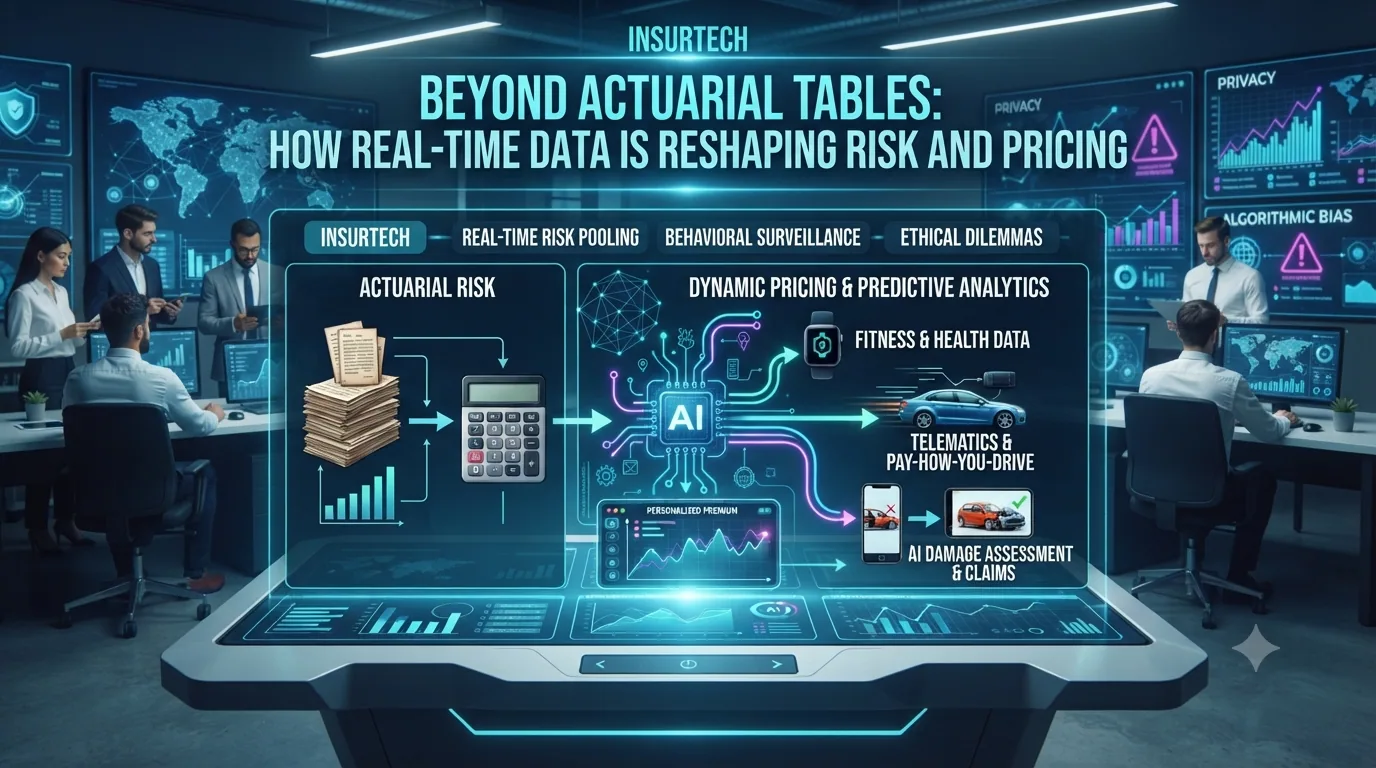
Take the auto insurance sector as a prime example. For generations, auto insurance rates were determined by your age, your gender, your credit score, and the zip code where you parked your car. Today, telematics has rewritten the playbook. Through plug-in devices, mobile apps, and connected vehicle systems, insurers now track actual driving behaviors in real time. They measure speed, harsh braking, rapid acceleration, cornering g-forces, and even distracted driving indicators like phone usage behind the wheel. Programs built around pay-how-you-drive or pay-as-you-drive models allow exceptional drivers to see dramatic reductions in their premiums. If you drive defensively, work from home, and rarely use your car during peak rush hour traffic, your insurance costs plummet because your individual risk profile reflects reality rather than demographic assumptions.
A parallel revolution is happening in life and health insurance through the integration of wearable technology. Fitness trackers, smartwatches, and connected health monitors continuously capture biometric data, including daily step counts, resting heart rates, sleep patterns, and workout intensities. Insurers now offer wellness-linked policies that reward policyholders with lower premiums, gift cards, or cash back for meeting specific health milestones. By encouraging policyholders to walk more, sleep better, and maintain active lifestyles, insurers reduce their long-term payout liabilities while customers enjoy immediate financial incentives and better health outcomes. It is a rare win-win scenario where technology aligns the commercial interests of the insurer with the personal well-being of the insured.
Beyond pricing and underwriting, artificial intelligence is radically reshaping the claims settlement process. Historically, filing an insurance claim after an accident meant waiting weeks for an adjuster to visit, inspect the damage, review paperwork, and manually process payouts. Today, automated image recognition and computer vision algorithms have compressed that timeline to minutes. When a policyholder gets into a minor car accident, they can snap photos of the damage using a smartphone app. AI models instantly analyze the photographs, identify structural and cosmetic damage, cross-reference parts pricing databases, and estimate repair costs almost instantaneously. In many cases, straight-through processing allows claims to be approved and paid out before the car has even arrived at the repair shop. This dramatic reduction in friction transforms customer satisfaction and slashes operational overhead for insurance carriers.
However, this brave new world of hyper-personalization is not without profound ethical dilemmas and privacy concerns. The fundamental tension underlying modern insurtech is the trade-off between consumer discounts and personal data surveillance. To qualify for lower rates, consumers must willingly open a window into their daily lives, sharing intimate details about their driving habits, sleep cycles, exercise routines, and geographic movements. This creates a commercial pressure cooker where opting out of data sharing means paying a financial penalty. For many, this feels like an invasive tax on privacy, where basic financial participation requires surrendering continuous behavioral telemetry to corporate entities.
More concerning still is the risk of algorithmic bias and financial exclusion. Actuarial risk pooling was designed, in part, to spread risk equitably across society, ensuring that basic protections remained accessible. When underwriting becomes hyper-personalized through complex machine learning models, algorithms can inadvertently discriminate against vulnerable demographics. Factors that correlate with lower income, such as living in a neighborhood with poor public transit, working irregular shift hours, or lacking access to gyms and fresh food, can be misinterpreted by algorithms as indicators of high risk. If predictive models penalize individuals for socioeconomic constraints beyond their control, we risk creating a segmented insurance market where basic coverage becomes unaffordable for the very people who need it most. The safety net risks fraying precisely at the edges where society's most vulnerable reside.
As these technological shifts accelerate, traditional insurance companies find themselves locked in a high-stakes race for survival against agile insurtech startups. Legacy carriers are burdened by decades-old mainframe systems, complex regulatory compliance frameworks, and deeply entrenched legacy processes. Insurtech startups, unencumbered by technical debt, build cloud-native platforms from the ground up, utilizing modern API architectures, real-time data ingestion pipelines, and machine learning models that can iterate and adapt in days rather than months. To compete, traditional insurers are aggressively modernizing their tech stacks, partnering with agile startups, or acquiring boutique technology firms to infuse innovation into their centuries-old DNA.
Ultimately, the future of underwriting represents a profound philosophical question for society. Are we moving toward a utopia of perfect risk matching, where everyone pays precisely and fairly for their own measured choices, or are we sliding into a panopticon of continuous surveillance where the unfortunate and the uninsured are priced out of existence? The answer lies in how regulators, technologists, and ethicists navigate the boundaries of data privacy, algorithmic fairness, and consumer protection in the years ahead. As real-time data continues to reshape risk and pricing, the insurance industry is no longer just predicting the future; it is actively shaping how we live our daily lives.