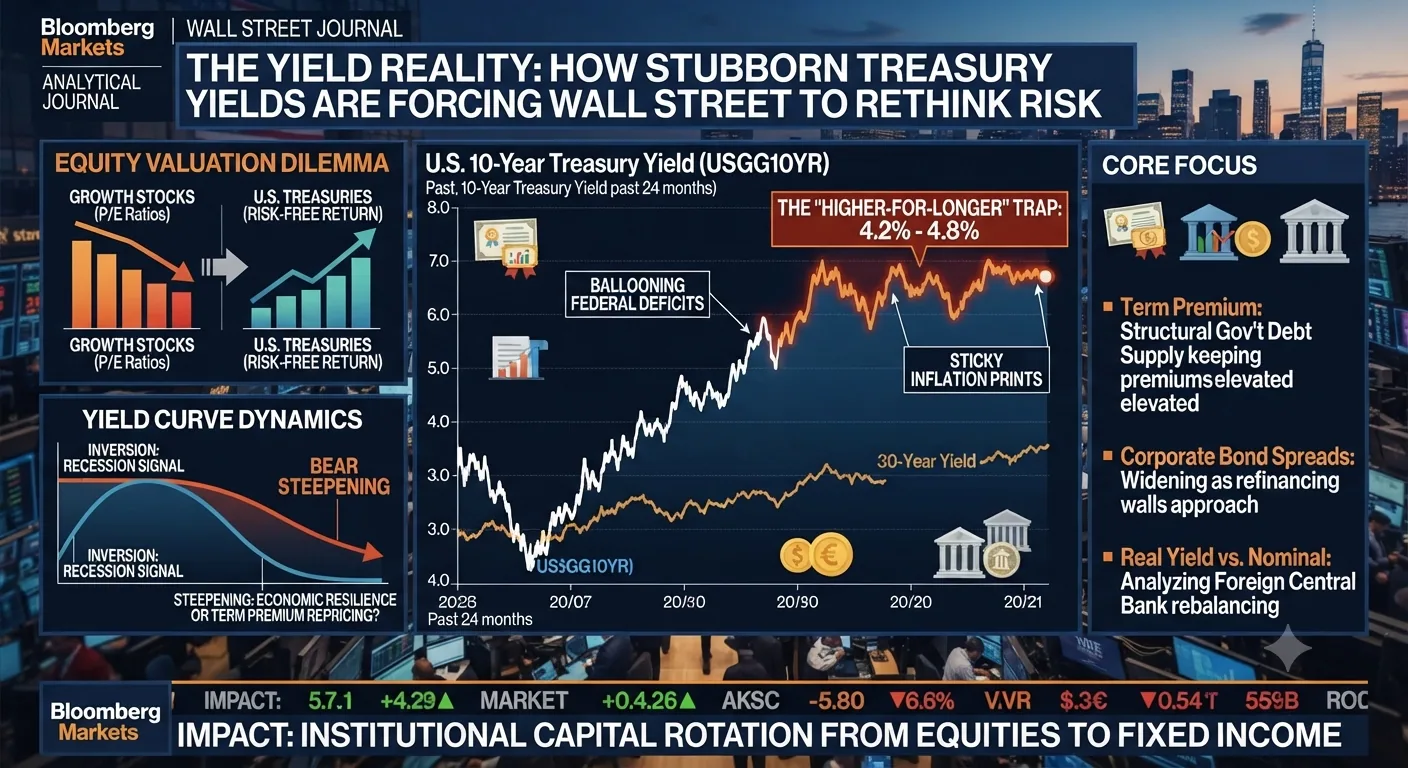
The Yield Reality: How Stubborn Treasury Yields Are Forcing Wall Street to Rethink Risk
⚠️ Truyện hư cấu phục vụ giải trí. Nhân vật & tình tiết là sản phẩm tưởng tượng.
The global financial landscape is shifting beneath our feet, and nowhere is that tremor felt more acutely than in the engine room of the international monetary system: the United States Treasury market. For more than a decade following the global financial crisis, investors operated under a comfortable, predictable assumption. That assumption was defined by ultra-low interest rates, an environment where central banks flooded the system with liquidity and pushed sovereign yields down to historic floors. In that era, cash yielded next to nothing, and bonds served primarily as a deflationary hedge while aggressive risk-taking in equities and alternative assets became the undisputed playbook for generating returns.
Today, that paradigm has been thoroughly dismantled. We are living through the reality of a higher for longer interest rate regime. Stubbornly persistent inflation prints, a structural transformation in global supply chains, resilient labor markets, and most importantly, an unprecedented expansion of federal sovereign debt issuance have rewritten the rules of engagement. Ten-year and thirty-year U.S. Treasury yields are no longer hovering near zero. Instead, they have established a formidable new baseline that is forcing Wall Street institutional asset managers, corporate treasurers, risk officers, and foreign central banks to completely rethink how they price capital, evaluate asset classes, and manage balance sheet liabilities.
To understand why this environment is so challenging, we must first look at the mechanics of supply and demand within the sovereign debt market. For generations, U.S. government debt was treated as the ultimate risk-free asset, a deep, highly liquid pool where capital could always find a safe harbor regardless of economic weather. But the sheer volume of new sovereign debt issuance required to finance expanding federal budget deficits has fundamentally altered market clearing dynamics. When the U.S. Department of the Treasury floods the market with hundreds of billions, and eventually trillions, of dollars in fresh bills, notes, and bonds, it creates a massive supply absorption test for primary dealers, institutional buyers, and foreign investors.
This structural increase in sovereign debt supply directly impacts what economists call the term premium. The term premium is the extra compensation that investors demand for holding long-term bonds instead of rolling over a series of short-term bills. For years, the term premium was compressed, sometimes even dipping into negative territory, kept artificially subdued by massive quantitative easing programs where the Federal Reserve acted as a relentless, price insensitive buyer of last resort. Now that the Federal Reserve is engaged in quantitative tightening, letting its balance sheet run off, and private investors are left to absorb the tsunami of new Treasury paper, the term premium has reawakened. Investors are demanding higher yields simply to take on the duration risk associated with long-term U.S. government debt, especially when they look out over a thirty-year horizon and worry about mounting fiscal liabilities, political gridlock, and long-term inflationary pressures.
This rise in sovereign yields creates an immediate gravitational pull across the entire financial ecosystem, starting with equity valuations. For years, low interest rates justified sky-high price to earnings multiples on growth stocks and technology companies, because when the risk-free rate is near zero, future cash flows discounted back to the present appear vastly more valuable. Wall Street analysts used discount rates that made tomorrow's speculative earnings look irresistible today. But as the benchmark ten-year Treasury yield establishes itself at significantly higher levels, the math changes completely. When institutional investors can secure a risk-free yield of four or five percent simply by buying government-backed paper, the hurdle rate for investing in riskier assets rises dramatically.
This dynamic triggers a quiet but powerful rotation of capital out of growth equities, commercial real estate, and venture capital, and back into fixed income instruments. Why take on the volatility of a high-flying tech stock or the liquidity risk of a commercial office building when you can lock in attractive, guaranteed yields backed by the full faith and credit of the United States government? This structural shift challenges equity market valuations, forcing analysts to reprice equities based on compressed multiples. Companies with high leverage and reliance on future growth are hit the hardest, as their future earnings are discounted at a much harsher rate.
Beyond equity markets, the higher-for-longer yield trap exerts intense pressure on corporate credit spreads and refinancing walls. During the era of cheap money, corporations across the economic spectrum gorged on low-cost debt, locking in ultra-low interest rates through corporate bond issuances. But those debt obligations are not infinite. They have maturity dates, and as those bonds mature, corporations are forced to refinance their capital structures at current market rates.
This looming refinancing wall represents one of the most significant hidden vulnerabilities in the corporate sector. A company that issued debt at three percent a few years ago might now find itself facing refinancing costs closer to seven or eight percent. For financially robust corporations with strong cash generation and pristine balance sheets, this is a manageable headwind. But for debt-heavy balance sheets, zombie companies, and lower-rated high yield issuers, the jump in borrowing costs can quickly turn manageable interest expenses into an unsustainable drain on cash flow.
As a result, credit spreads—the extra yield that corporate bonds offer over comparable U.S. Treasuries to compensate for default risk—are poised to face severe widening pressures if economic growth stumbles. When risk-free yields are high, credit spreads often fail to reflect the true underlying distress in corporate balance sheets until liquidity suddenly dries up. This creates a dangerous environment where corporate defaults can spike unexpectedly, catching over-leveraged market participants off guard.
We must also examine the behavior of foreign central banks and sovereign wealth funds, whose appetite for U.S. paper has undergone a profound transformation. Historically, foreign official institutions recycled their trade surpluses heavily into U.S. Treasuries, acting as a massive, stable anchor of demand for American debt. However, geopolitical realignments, concerns over sanctions, and the shifting calculus of real versus nominal yields have altered this dynamic.
Real yields, which adjust nominal yields for expected inflation, matter deeply to international investors. When inflation is sticky and nominal yields fluctuate, foreign buyers must weigh currency risk, domestic capital needs, and alternative reserve assets. While high nominal yields make U.S. Treasuries superficially attractive, persistent inflation erodes the purchasing power of those returns. Consequently, many sovereign wealth funds and international central banks have diversified their reserve portfolios, moving selectively toward alternative assets, gold, and regional debt markets, even as the overall volume of U.S. debt issuance continues to scale new heights.
The mechanics of the Treasury yield curve itself serve as a fascinating macro barometer for the ongoing tug-of-war between recession fears and economic resilience. For an extended period, the yield curve was deeply inverted, with short-term yields significantly higher than long-term yields as the Federal Reserve hiked interest rates to cool an overheated economy. Historically, a sustained yield curve inversion has been one of the most reliable leading indicators of an impending economic recession. It signals that monetary policy is restrictive, credit is tightening, and future economic activity is likely to slow down.
Yet, as the economic data continued to surprise to the upside—driven by robust consumer spending, fiscal stimulus, and corporate adaptation—the narrative began to shift. The process of the yield curve un-inverting and steepening tells a complex story. A bull steepening or bear steepening of the curve reflects shifting market expectations about inflation persistence, terminal interest rates, and the sheer weight of federal borrowing. If long-term yields rise faster than short-term yields, it often signals that bond vigilantes are demanding more compensation for fiscal indiscipline and long-term inflation risk, rather than simply anticipating imminent Federal Reserve rate cuts.
This brings us to the core dilemma facing Wall Street today. The financial markets have spent the better part of the last two years trying to front-run an aggressive pivot by the Federal Reserve, repeatedly pricing in rapid rate cuts that ultimately failed to materialize as inflation proved stickier than anticipated. Each time the market tried to celebrate an imminent return to easy money, incoming economic data forced a painful reality check. This game of monetary expectations has created heightened volatility across asset classes, punishing complacency and rewarding disciplined risk management.
Navigating this environment requires a fundamental departure from the playbook of the previous decade. Investors can no longer rely on the rising tide of central bank liquidity to lift all asset classes indiscriminately. Stock picking must be anchored in balance sheet strength, pricing power, and low leverage. Fixed income, long dismissed as a dead asset class during the zero-interest-rate era, has reclaimed its rightful place as a cornerstone of portfolio construction, offering genuine income generation for the first time in a generation. Yet, it also demands rigorous credit analysis, as the dispersion between high-quality issuers and distressed borrowers widens significantly.
As we look ahead, the structural realities of ballooning federal deficits, persistent inflationary pressures, and elevated sovereign debt supply will continue to cast a long shadow over global financial markets. The higher-for-longer yield trap is not a temporary anomaly or a brief market glitch; it is the new structural reality of the macroeconomic landscape. Wall Street and global institutional investors must adapt to a world where capital has an explicit, measurable cost, where risk-free returns compete fiercely with equity growth, and where fiscal discipline matters once again. Those who recognize this paradigm shift and adjust their portfolios accordingly will navigate the turbulent waters ahead, while those clinging to the ghosts of the zero-interest-rate era risk being caught unawares by the enduring realities of the sovereign debt cycle.
Bài viết liên quan
Beyond the Hype: Wall Street Demands Return on Investment from the Trillion-Dollar AI Capex Supercycle
Weaponized Finance: Can the U.S. Dollar Maintain Hegemony Against a Fragmenting World?
Harvest of Glass: The Bitter Civil War Splitting Midwestern Farming Towns Over Solar Leases